What is the structural scope and industry significance of the Lightweight Pulleys Market?
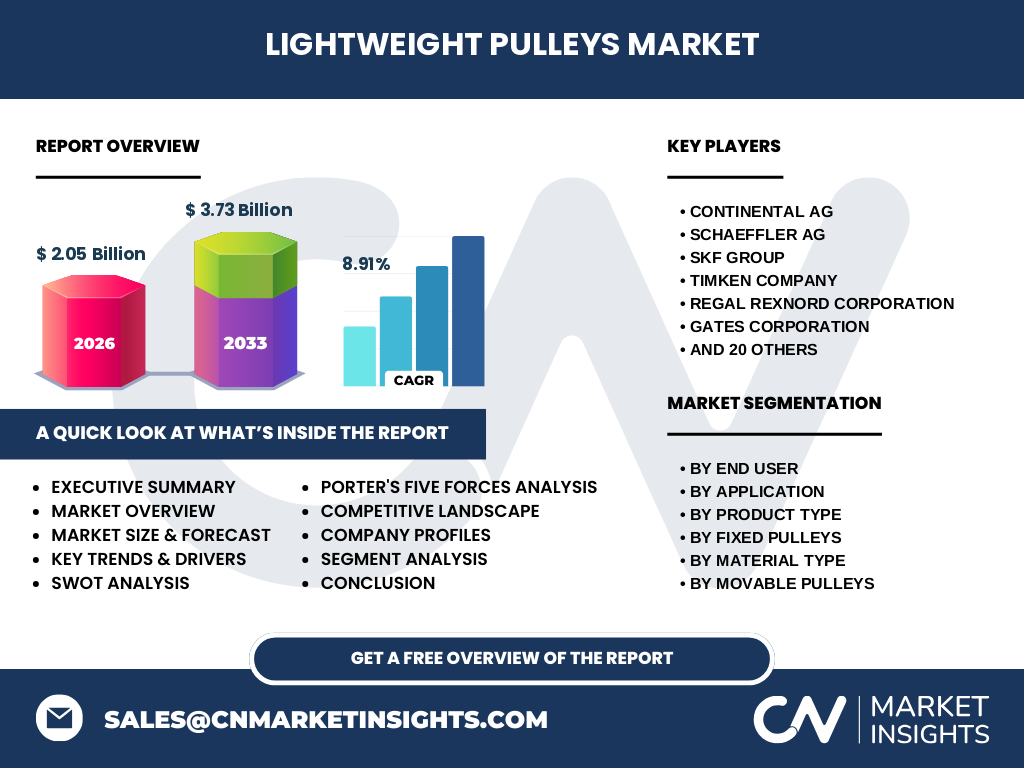
Our analysis indicates the Lightweight Pulleys Market is valued at $2.05 Billion in 2026. This sector encompasses advanced mechanical components engineered from materials like aluminum, plastic, composite, and steel to reduce rotational inertia across automotive, aerospace, and industrial machinery applications. These components are critical for enhancing energy efficiency and reducing parasitic power losses under stringent regulatory frameworks imposed by bodies like the EPA and EASA.
Structural Growth Drivers and Market Restraints
Growth in the Lightweight Pulleys Market is propelled by surging demand for fuel-efficient vehicles and high-performance aerospace systems requiring low moment of inertia. However, supply chain volatility involving raw aluminum and specialized engineering plastics acts as a notable restraint. Logistical bottlenecks at major container ports frequently disrupt raw material inflows, challenging Original Equipment Manufacturers (OEMs) seeking strict inventory turnover.
The Shift Toward Advanced Composite Materials and Digital Supply Chains
Industry trends reveal a pronounced migration toward composite material fixed pulleys and block and tackle systems to maximize strength-to-weight ratios. Leading innovators such as Gates Corporation and Schaeffler AG are integrating IoT-enabled predictive maintenance sensors directly into pulley assemblies, fundamentally altering how industrial machinery operators monitor wear and prevent catastrophic downtime.
COVID-19 Pandemic Disruption and Post-Crisis Recovery Trajectory
The pandemic severely disrupted global supply chains, causing raw material shortages for key market participants like SKF Group and Timken Company. Recovery has been robust, anchored by pent-up demand in industrial machinery and automotive manufacturing. The data suggests post-COVID operational resilience relies heavily on localized sourcing strategies and diversified tier-1 supplier networks across North America and Europe.
Competitive Benchmarking and Strategic Dynamics
The Lightweight Pulleys Market features a moderately consolidated competitive landscape populated by global giants such as Continental AG, Regal Rexnord Corporation, and Tsubakimoto Chain Co. Market leaders maintain dominance through aggressive R&D in proprietary lightweight alloys and strategic acquisitions of specialized component manufacturers. Smaller regional players compete primarily on agile localized distribution and customized heavy-duty movable pulley solutions.
Executive Summary: Key Findings in the Lightweight Pulleys Market
Executive intelligence confirms the Lightweight Pulleys Market will reach $3.73 Billion by 2033, expanding at a robust CAGR of 8.91% from 2027. Strategic consolidation, material innovation, and strict global decarbonization mandates are the primary catalysts transforming this mechanical sector from a commoditized parts market into a high-tech engineering discipline.
Market Forecast and Valuation Trajectory (2027 to 2033)
Projections indicate explosive expansion, scaling the market from its 2026 baseline to $3.73 Billion by 2033 at a steady 8.91% CAGR. This trajectory is heavily supported by rising automation investments across Asian manufacturing hubs and the continuous electrification of commercial vehicle fleets requiring specialized single wheel and multiple wheel fixed pulleys.
Granular Segmentation Analysis
Segmentation is categorized by end user (OEMs, Aftermarket), application (Automotive, Aerospace, Industrial Machinery, Construction, Marine), product type (Fixed, Movable, Compound), and material type (Aluminum, Plastic, Composite, Steel). OEMs dominate initial volume, while the Aftermarket segment relies extensively on distributors like Martin Sprocket & Gear Inc. to supply replacement single sheave and double sheave movable pulleys.
Geographic Distribution and Regional Performance
Regional performance varies significantly, with North America and Europe leading in aerospace and automotive adoption due to stringent emissions standards enforced by the EPA and European Commission. Meanwhile, Asia-Pacific represents the fastest-growing frontier, driven by rapid industrialization, expansion of manufacturing facilities in China and India, and rising integration of industrial grade compound pulleys.
In-Depth Regional Review of Manufacturing Hubs
North American demand is anchored by aerospace innovation in Washington and automotive corridors in the Midwest, where players like RBC Bearings (Dodge Industrial) maintain strong footholds. European markets prioritize lightweight mobility and sustainability compliance, favoring specialized offerings from Optibelt GmbH and SIT S.p.A. Logistics efficiency through regional ports remains vital for sustaining localized manufacturing.
Company Profiles and Strategic Positioning
Industry leaders like Misumi Group Inc. leverage vast digital component catalogs for rapid prototyping, whereas Mitsuboshi Belting Ltd. and Bando Chemical Industries Ltd. focus on high-durability power transmission systems. Companies such as Fenner Drives Inc. and Toronto Gear Works differentiate themselves through niche custom engineering for robotics and automated warehousing applications.
Porter's Five Forces Analysis of Competitive Pressures
Supplier power remains moderate due to specialized raw material requirements for aluminum and composites, while buyer power is high among major automotive OEMs demanding volume pricing. Threat of substitutes is mitigated by the unmatched mechanical advantage of engineered pulley systems, though competitive rivalry is intense among established multinational manufacturers.
SWOT Analysis of the Lightweight Pulleys Sector
Key strengths include exceptional strength-to-weight ratios and energy efficiency gains. Weaknesses involve high initial tooling costs for composite manufacturing. Opportunities abound in electric vehicle powertrain optimization and renewable energy tracking systems. Threats center on raw material price volatility and macroeconomic headwinds affecting capital expenditure in heavy industries.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with primary raw material extraction (aluminum bauxite refiners, polymer chemical plants), progressing through precision casting, machining by firms like HZPT Transmission Components Co. Ltd., and distribution via direct sales or digital platforms to end-users like Brewer Machine & Gear Co. and Pfeifer Industries LLC.
High-Potential Investment Insights and Strategic Recommendations
Investors should target companies specializing in recyclable composite materials and automated manufacturing lines capable of producing complex multi-sheave compound pulleys. Strategic partnerships with aerospace primes and EV manufacturers offer the highest return on investment given stringent efficiency requirements.
Conclusion and Strategic Takeaways
The Lightweight Pulleys Market represents a vital growth pocket within industrial manufacturing, poised to scale robustly to $3.73 Billion by 2033. Success in this sector hinges on continuous material science innovations, agile supply chain management, and alignment with global energy-efficiency mandates championed by forward-thinking industrial leaders.
Research Methodology and Data Triangulation
Our analysis is built upon rigorous data triangulation, combining primary qualitative interviews with C-level executives at firms like Pix Transmissions Ltd. and B&B Manufacturing with secondary macroeconomic data, global trade registries, customs shipping records, and proprietary econometric models to establish accurate baseline figures.
Scope of the Report and Analytical Limitations
This report covers global market dynamics for lightweight pulleys from 2026 to 2033, analyzing quantitative revenue metrics alongside qualitative operational trends. Limitations include unpredictable geopolitical trade policy shifts and localized currency fluctuations that may impact short-term regional pricing structures.
Recent Developments, Partnerships, and Strategic Moves
Recent market activity highlights accelerated R&D investments by industry stalwarts like French tiremaker Michelin and Reliance Precision Limited into ultra-lightweight power transmission components. Strategic joint ventures focusing on sustainable bio-plastics and digitalized supply chain tracking have become the primary vehicle for sustaining competitive differentiation.